 foxnews
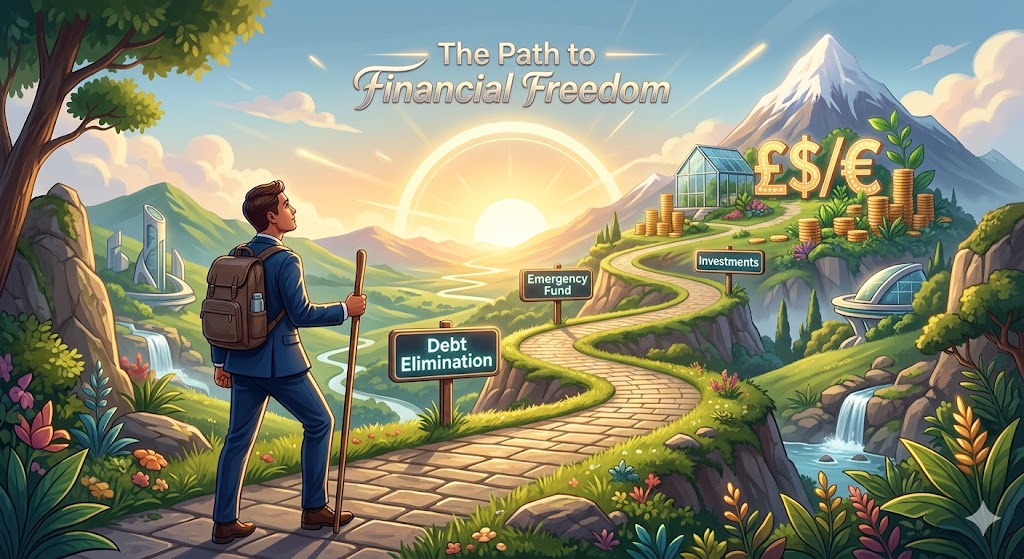
Master Your Money: A Comprehensive Guide to Building Generational Wealth
Achieving financial independence is rarely a matter of luck or inheritance. For the vast majority of successful individuals, wealth is the result of disciplined habits, strategic planning, and a long-term perspective. Consequently, understanding the core pillars of personal finance is essential for anyone looking to escape the cycle of living paycheck to paycheck.
In today’s volatile economic climate, traditional saving methods are often insufficient. Inflation can quickly erode the value of cash sitting in a standard bank account. Therefore, it is crucial to implement a multi-faceted approach that prioritizes debt reduction, emergency preparedness, and diverse income generation.
This guide explores the fundamental strategies required to transform your financial reality. By following these steps, you will not only secure your own future but also lay the groundwork for generational wealth. Indeed, the journey to financial freedom begins with a single, well-informed decision.
Building an Unshakable Emergency Fund
Before you even consider investing in the stock market or purchasing real estate, you must establish a safety net. An emergency fund serves as your financial insurance policy against unexpected life events. For instance, sudden medical bills, car repairs, or job losses can derail your progress if you are unprepared.
Most financial experts recommend saving at least three to six months of essential living expenses. This money should be kept in a highly liquid account, such as a high-yield savings account (HYSA). Consequently, you will have immediate access to funds without needing to liquidate long-term investments during a market downturn.
Furthermore, having this cash reserve provides a psychological benefit. When you know you are covered for emergencies, you are less likely to make impulsive, fear-based financial decisions. Specifically, an emergency fund acts as the bedrock upon which all other wealth-building activities are built.
Strategic Debt Management and Reduction
High-interest debt is the greatest enemy of wealth accumulation. Credit card balances, in particular, often carry interest rates that far exceed the returns of typical investments. To illustrate, paying 20% interest on a debt is mathematically equivalent to losing a 20% investment return every single month.
To tackle your liabilities effectively, consider using one of the following proven methods:
- The Debt Snowball: Focus on paying off the smallest balances first to build psychological momentum and stay motivated.
- The Debt Avalanche: Prioritize debts with the highest interest rates to minimize the total amount of interest paid over time.
- Debt Consolidation: Move high-interest debt to a lower-interest loan or a 0% APR balance transfer card to accelerate repayment.
Regardless of the method you choose, the key is consistency. As you eliminate monthly payments, you free up more disposable income to redirect toward your savings and investment goals. Ultimately, becoming debt-free is a critical milestone on the path to true financial autonomy.
Unlocking the Power of Passive Income
The concept of “making money while you sleep” is not a myth; it is a necessity for serious wealth building. Passive income streams allow you to decouple your earnings from your time. Consequently, you are no longer limited by the number of hours you can physically work in a day.
There are several ways to generate passive revenue, depending on your risk tolerance and available capital. For example, dividend-paying stocks provide regular payouts simply for holding shares in profitable companies. Additionally, real estate investments can offer consistent monthly rental income alongside long-term property appreciation.
Moreover, the digital age has opened doors for low-cost passive income ventures. Specifically, creating digital products, such as e-books, online courses, or software, requires an initial time investment but can generate sales for years. By diversifying your income sources, you create a robust financial ecosystem that is resilient to economic shifts.
The Magic of Compounding and Long-Term Investing
Time is arguably your most valuable asset when it comes to investing. The principle of compound interest allows your earnings to generate their own earnings. Over decades, even modest contributions can grow into a substantial fortune if left untouched and reinvested.
To maximize this effect, it is important to utilize tax-advantaged accounts. Specifically, accounts like the 401(k) or a Roth IRA offer significant tax benefits that can accelerate your wealth growth. Furthermore, adopting a buy-and-hold strategy with low-cost index funds is often more effective than attempting to time the market.
In addition, consistency is more important than finding the perfect moment to buy. By practicing dollar-cost averaging, you invest a fixed amount regularly regardless of market fluctuations. As a result, you buy more shares when prices are low and fewer when prices are high, lowering your average cost over time.
Developing a Wealth-Building Mindset
Financial success is 20% head knowledge and 80% behavior. Even with the best tools, you will struggle to build wealth if you do not master frugality and delayed gratification. This does not mean living a life of deprivation, but rather making intentional choices about where your money goes.
Start by tracking every dollar you spend for at least one month. This exercise often reveals “leakage”—small, unnecessary expenses that add up to significant amounts over a year. To illustrate, cutting a $50 monthly subscription could result in thousands of dollars of extra investment capital over a decade.
Finally, remember that wealth building is a marathon, not a sprint. There will be setbacks and market corrections along the way. However, by maintaining your focus on the long-term goal and adhering to these core principles, you will eventually achieve the financial peace and freedom you deserve.