 foxnews
Achieving financial independence is rarely a matter of luck or overnight success. Instead, it is the result of disciplined habits, strategic planning, and a deep understanding of how money works. Many people mistake being “rich” for being “wealthy,” but these concepts are fundamentally different.
While being rich often refers to a high monthly income, true wealth is measured by the time your assets can sustain your lifestyle without active work. Consequently, the journey toward financial freedom begins with a shift in mindset. You must transition from being a consumer to becoming an investor.
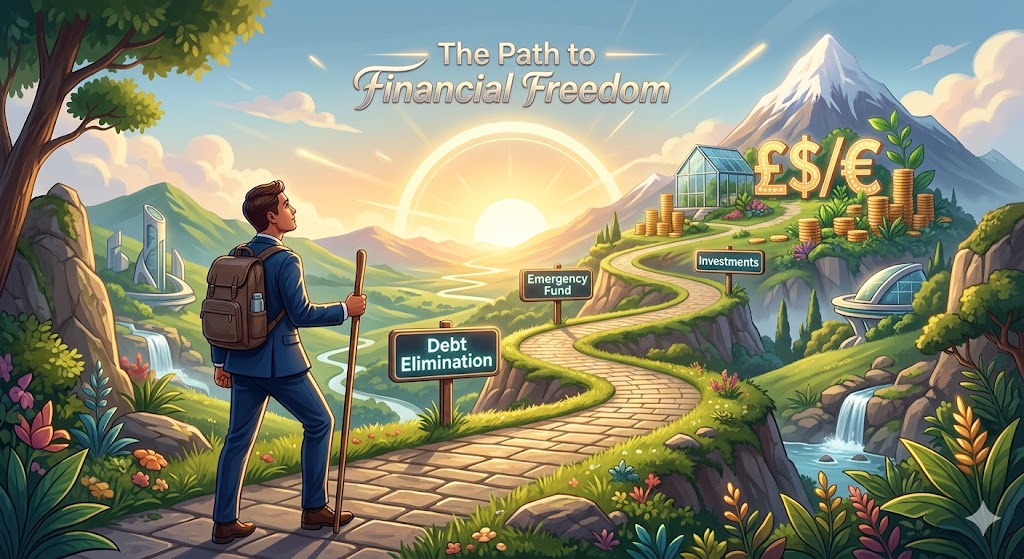
In this comprehensive guide, we will explore the essential pillars of wealth building. Specifically, we will focus on debt management, emergency funds, and the power of passive income to help you secure your financial future.
Eliminating the Obstacles: Strategic Debt Management
Before you can effectively grow your net worth, you must address the anchors holding you back. High-interest debt, such as credit card balances, is the most significant deterrent to wealth accumulation. Moreover, the interest rates on these debts often far exceed the returns you would get from the stock market.
To illustrate, imagine paying 22% interest on a credit card while earning 8% on an investment. Mathematically, you are losing money every month. Therefore, your first priority should be a debt “snowball” or “avalanche” method to regain control of your cash flow.
Focusing on “Good Debt” vs. “Bad Debt” is also crucial. While high-interest consumer debt is toxic, low-interest debt used for appreciating assets—like a mortgage or a business loan—can sometimes be a tool for growth. However, the goal should always be to minimize unnecessary liabilities.
Constructing Your Safety Net: The Emergency Fund
Life is inherently unpredictable, and financial setbacks are often a matter of “when,” not “if.” An emergency fund serves as your financial insurance policy against the unexpected. Without this cushion, a sudden medical bill or car repair can force you back into a cycle of high-interest borrowing.
Typically, financial experts recommend saving three to six months of essential living expenses. This fund should be kept in a liquid, high-yield savings account where it is easily accessible but separate from your daily spending money. Furthermore, having this cash reserve provides the psychological peace of mind needed to take calculated investment risks.
To build this fund effectively, consider the following steps:
- Automate your savings so a portion of your paycheck goes directly to your emergency account.
- Identify essential expenses like rent, utilities, and groceries to determine your target number.
- Avoid the temptation to use these funds for non-emergencies, such as vacations or luxury purchases.
- Review your fund annually to ensure it keeps up with inflation and changes in your lifestyle.
The Engine of Growth: Generating Passive Income
Once your foundation is secure, it is time to put your money to work. Passive income is the ultimate goal of any wealth-building strategy. Essentially, this is money earned with minimal ongoing effort, allowing you to decouple your time from your earnings. As a result, you gain the freedom to choose how you spend your days.
There are several avenues to explore when seeking passive income streams. For instance, dividend-paying stocks allow you to own a piece of profitable companies that distribute a portion of their earnings to shareholders. Over time, reinvesting these dividends can lead to explosive growth through the power of compounding.
In addition to the stock market, real estate investments remain a classic path to wealth. Whether through physical rental properties or Real Estate Investment Trusts (REITs), real estate offers both monthly cash flow and long-term appreciation. Consequently, diversifying across different asset classes reduces risk while maximizing potential returns.
The Power of Consistency and Time
Perhaps the most underestimated factor in wealth building is time. The “Magic of Compounding” works best over decades, not months. Therefore, starting early is far more important than starting with a large sum of money. Even small, consistent contributions can grow into a significant fortune given enough time.
Moreover, you must remain disciplined during market volatility. Many investors panic and sell during downturns, which locks in their losses. In contrast, successful wealth builders view market dips as opportunities to buy assets at a discount. Consistency, rather than timing the market, is the true secret to long-term success.
Ultimately, building wealth is a marathon, not a sprint. By managing your debt, securing an emergency fund, and investing in passive income streams, you are laying the groundwork for a life of abundance. Start today, stay the course, and watch your financial freedom become a reality.
Key Takeaways for Financial Success
- Prioritize high-interest debt repayment to stop the drain on your monthly cash flow.
- Maintain a liquid emergency fund to protect yourself from life’s inevitable surprises.
- Invest in diverse assets like stocks and real estate to build sustainable passive income.
- Leverage the power of compounding by starting your investment journey as early as possible.
- Automate your finances to ensure consistent progress without relying solely on willpower.
In conclusion, personal finance is more “personal” than “finance.” It requires a customized approach that aligns with your specific goals and risk tolerance. However, by following these core principles, you can navigate the complexities of the financial world with confidence and clarity.